HMRC proposes new rules on free game tax
HMRC has proposed changing how online game tax applies to free bets and promotions. The proposals will take effect on 1 April 2027 and came after a case Jumpman Gaming won.

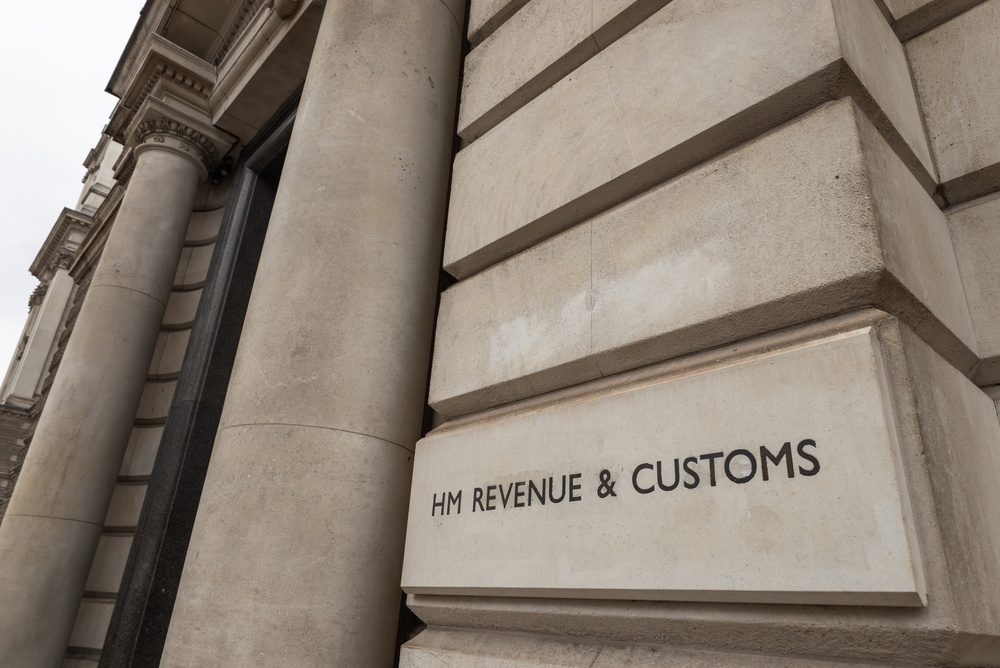
In the UK, HM Revenue and Customs (HMRC) has proposed changing how remote gaming duty (RGD) applies to free games. The policy paper published by the department targets the rules in the Finance Act 2014. The change directly affects the tax that betting companies pay on promotions such as free bets and free returns.
Under the proposal, the term "free game" will be renamed "restricted game". The conditions under which a free game won from another free game can be exempt from tax will also be clarified. Under these conditions, the won game must be used only in an online game and no other benefit may be provided. Tournaments and similar applications will also be considered within this scope.
The definition of a prize is also changing. For something to count as a prize, it must be paid or provided under the game's published rules. Refunds made when a game is interrupted or cancelled may also be treated as prizes. Among the proposals is a provision that participation in a free tournament be treated as a game of chance.
These proposals are part of the Finance Bill and will take effect on 1 April 2027. On the same day, general betting duty will rise from 15% to 25%, and the machine games duty rate for Category B gaming machines will increase from 20% to 25%. HMRC argues that clear rules will give operators more certainty and reduce disputes.
The timing is notable. The proposals came after Jumpman Gaming won a case concerning its betting promotions. The Upper Tribunal completely eliminated the company's tax debt of £3.2 million. While HMRC aims to protect revenue, the tribunal ruled that applying RGD to amounts re-staked from free bets was wrong.
Comments (0)
Be the first to comment.
Log in to comment.