Wynn's UAE Casino Project Could Lift Its Credit Rating
According to CBRE Credit Research analysts, when the Wynn Al Marjan Island project opens, Wynn Resorts' debt ratio could fall to 5x, paving the way for a credit rating upgrade. Although the project has weighed on the stock this year due to the war in Iran, some analysts argue that investors have assigned almost no value to the project's potential.

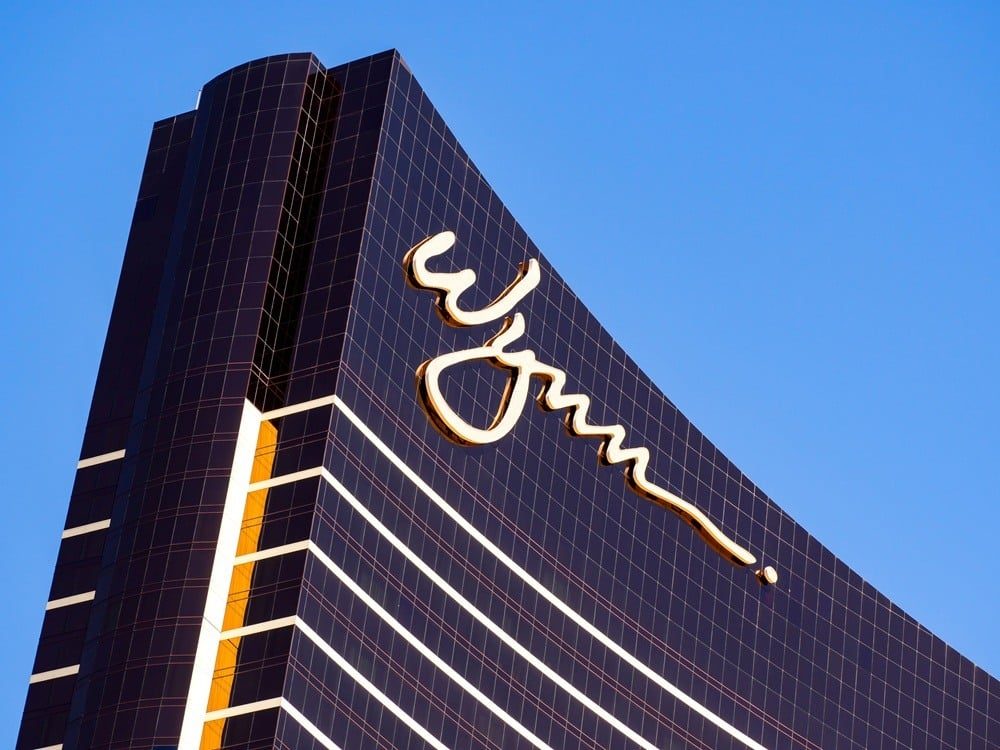
Wynn Al Marjan Island, the first casino resort project in the Middle East, is scheduled to open its doors in September 2027. In a report published on Monday, CBRE Credit Research analysts Colin Mansfield and Connor Parks said the project could make a significant contribution to the financing of operator Wynn Resorts and could pave the way for credit rating upgrades.
According to the analysts, after the project opens, Wynn could operate with low leverage for an extended period and generate strong free cash flow without significant development spending. The lease-adjusted leverage ratio could fall to 5x. This would mean a decline of more than 1x from current levels. The company's 40% stake in the project is also seen as a positive factor for its credit profile.
Fitch and S&P Global Ratings rate Wynn BB-, while Moody's assigns it a B1 rating. All three agencies rate the company below investment grade. This means that when issuing debt, the company has to pay higher interest to investors, and its interest expenses have increased over time. The analysts recall that Moody's has set a 6x leverage threshold for Wynn and note that the rating could rise if the ratio falls to that level. Fitch and S&P have a 5x leverage trigger. For Wynn to reach BBB-, the lowest investment grade rating, it would need to be upgraded three notches.
According to the report, the project has weighed on share performance this year due to the war in Iran. Some analysts consider this decline unfair, as the investment community has assigned almost no value to the project's potential.
According to CBRE, the project is structured so that creditors could target only this facility even in an unusual scenario. The project debt is non-recourse, and the project is largely owned by the state. For this reason, the analysts believe that most investors will include the project's cash inflows in Wynn's EBITDA, but will not add the project-level debt to the parent company's consolidated debt.
Comments (0)
Be the first to comment.
Log in to comment.